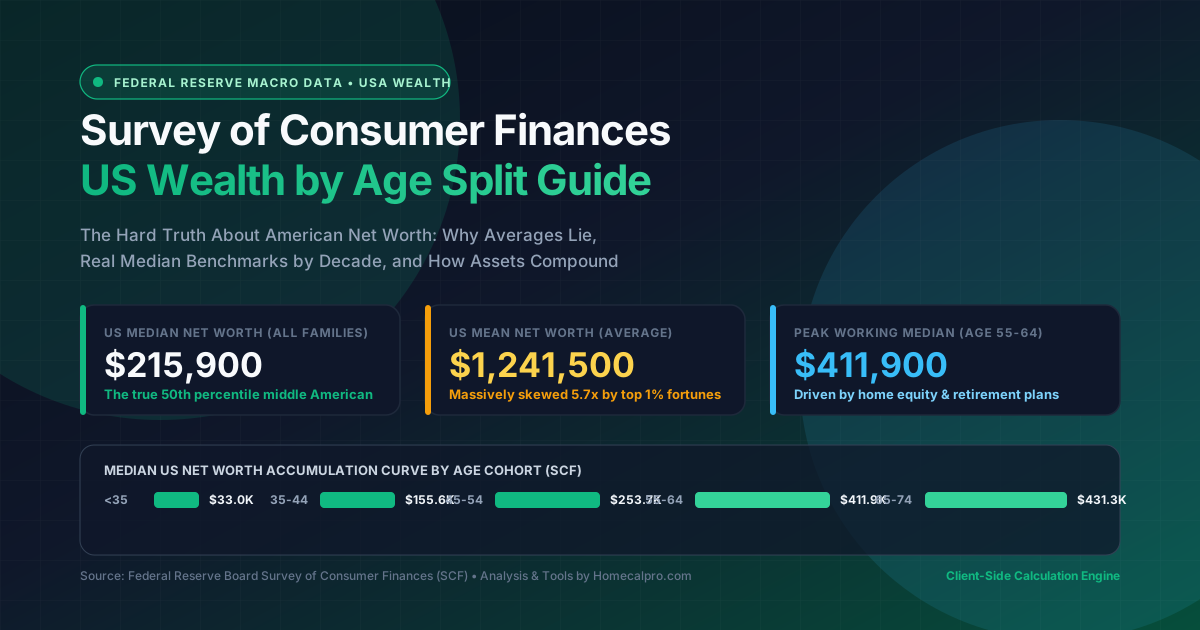
If you have ever glanced at a financial news report announcing that the 'average American in their 50s has nearly $1.9 million in net worth' and felt a sinking knot in your stomach, you are not alone. And more importantly, you are not mathematically behind. That $1.9 million figure is a classic statistical trap: it represents the arithmetic mean, an aggregate metric pulled upward by America's top 1% multi-millionaires and billionaires.
The Federal Reserve's landmark Survey of Consumer Finances (SCF) tells an entirely different, far more grounded story. The median net worth for a typical American household head aged 55 to 64 is actually $411,900—less than a quarter of the publicized average. For Americans under 35, the median net worth sits at $33,000, while the average is reported at $135,400.
This comprehensive editorial report breaks down the official Federal Reserve Survey of Consumer Finances age split data. You will see the exact median and mean benchmarks for every decade of adulthood, discover what assets (home equity vs. 401(k) accounts vs. liquid cash) actually make up American balance sheets, and learn how to use client-side financial tools to measure and accelerate your own household wealth trajectory.
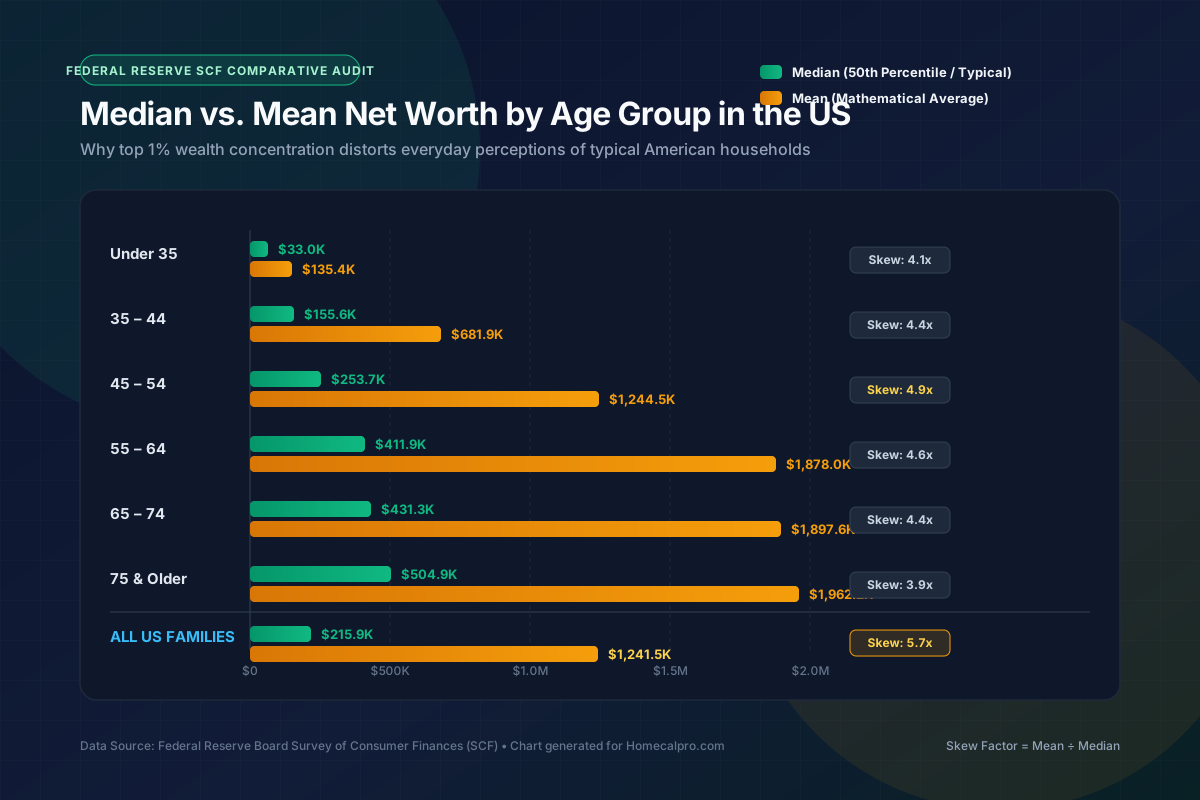
Quick answer:The Federal Reserve's Survey of Consumer Finances (SCF) reveals that arithmetic averages (mean) wildly misrepresent typical American household wealth due to top 1% concentration. The true median net worth by age cohort is: Under 35: $33,000 (mean $135,400); 35–44: $155,600 (mean $681,900); 45–54: $253,700 (mean $1,244,500); 55–64: $411,900 (mean $1,878,000); 65–74: $431,300 (mean $1,897,600); and 75+: $504,900 (mean $1,962,200). Across all American families, the median net worth is $215,900, compared to an average of $1,241,500 (a 5.7x skew). For the middle 80% of US households, wealth is anchored by two primary engines: primary residence home equity (45%–58%) and workplace retirement accounts (30%–42%).
1. Key Findings: Official Federal Reserve SCF Wealth Benchmarks
Median versus Mean family net worth across every American age bracket
The table below outlines the core economic findings from the Federal Reserve Board's triennial Survey of Consumer Finances. Notice the substantial divergence between the median (the true middle-class reality) and the mean (the top-heavy average) across every single demographic tier.
The 'Wealth Concentration Skew Factor' represents the mean divided by the median. A higher multiplier indicates a greater degree of extreme billionaire and multi-millionaire wealth pulling the average away from the everyday experience of American wage earners.
Why Median Beats Mean for Personal Benchmarking
If nine public school teachers sit in a room with one hedge fund billionaire, the mean net worth is over $100 million, while the median accurately reflects the typical educator. The median is the only statistically valid benchmark for evaluating personal progress.
| Age Bracket of Household Head | Median Net Worth (50th Percentile) | Mean Net Worth (Mathematical Average) | Wealth Skew Factor (Mean ÷ Median) | Primary Financial Asset Driver |
|---|---|---|---|---|
| Under 35 | $33,000 | $135,400 | 4.1x | Cash savings, early 401(k) balances, vehicle equity |
| 35 to 44 | $155,600 | $681,900 | 4.4x | Primary home equity and growing retirement accounts |
| 45 to 54 | $253,700 | $1,244,500 | 4.9x | Peak earnings, amortized home loans, 401(k) compounding |
| 55 to 64 | $411,900 | $1,878,000 | 4.6x | Substantial housing equity, peak retirement balances |
| 65 to 74 | $431,300 | $1,897,600 | 4.4x | Paid-off mortgages, IRA roll-overs, beginning of decumulation |
| 75 and Older | $504,900 | $1,962,200 | 3.9x | Debt-free real estate, survivor wealth consolidation |
| All US Families | $215,900 | $1,241,500 | 5.7x | Home equity + workplace retirement plans |
2. Why the Survey of Consumer Finances Is the Gold Standard (and Why Averages Lie)
Understanding the Federal Reserve's sampling methodology and the distortion of wealth concentration
Every three years, the Federal Reserve Board sponsors the Survey of Consumer Finances in cooperation with the Department of the Treasury and NORC at the University of Chicago. Unlike commercial polls that survey a small sample of credit card users, the SCF is the undisputed gold standard of US wealth research. It evaluates thousands of families across every geographic and demographic tier, utilizing an intricate dual-frame sample that oversamples high-wealth households so researchers can capture macro economic aggregates without sacrificing precision on typical working-class households.
Consider what happens when looking at the overall US numbers: the overall mean net worth is $1,241,500, yet the overall median is $215,900. That 5.7x multiplier proves that the top 1% to 10% own an overwhelming share of commercial real estate, corporate equities, and private business valuations.
When evaluating your personal retirement readiness, measuring yourself against the mean average will distort your targets and generate unnecessary panic. The median is the true economic midpoint where exactly 50% of households have accumulated more and 50% have accumulated less.
 AI Generated Image
3. The Deep Age Split: Deconstructing Net Worth Across Every Decade
How lifetime earnings, debt amortisation, and compound interest shape each life stage
Wealth accumulation in the United States is fundamentally tied to chronological age because net worth is rarely created in sudden windfalls. It is the steady mathematical output of career wage progression, disciplined monthly debt reduction, and multi-decade compound interest. Here is how each age cohort navigates the financial lifecycle:
• Under 35 (Median: $33,000 / Mean: $135,400): The foundation and debt compression era. High student loan balances, initial vehicle financing, and rental security deposits create heavy balance-sheet drag. Only 35% of households under 35 own their home. However, this group possesses an invaluable financial asset: a 30-to-40-year compounding runway where early index fund contributions generate exponential lifetime gains.
• Ages 35 to 44 (Median: $155,600 / Mean: $681,900): The career velocity and mortgage acceleration pivot. Net worth nearly quintuples from $33,000 to $155,600 as homeownership rates cross 60%. Monthly mortgage amortisation acts as an automated forced savings vehicle, while career earnings hit senior managerial levels.
• Ages 45 to 54 (Median: $253,700 / Mean: $1,244,500): Peak gross earnings and the college squeeze. Wage earners reach their lifetime peak compensation. However, this is often the 'sandwich decade', where households simultaneously finance children's college tuition and begin assisting elderly parents. Disciplined savers see their 401(k) portfolios cross the critical $150,000 inflection point.
• Ages 55 to 64 (Median: $411,900 / Mean: $1,878,000): Pre-retirement and peak wealth accumulation. College tuition ends, mortgage balances approach zero, and IRS catch-up contributions allow households to shelter significant tax-deferred income. This decade represents the summit of working-age capital accumulation.
• Ages 65 to 74 (Median: $431,300 / Mean: $1,897,600): The early retirement plateau. Households shift from capital accumulation to decumulation under the 4% safe withdrawal rule. Over 80% own their home, with more than half living mortgage-free, drastically slashing monthly overhead.
• Ages 75 and Older (Median: $504,900 / Mean: $1,962,200): Preservation and longevity realities. Surviving households consolidate estates and insurance proceeds, while paid-off primary homes reflect 40+ years of long-term real estate appreciation. The primary budget concern shifts to healthcare and assisted living.
4. What Actually Makes Up American Wealth? (Asset Composition Breakdown)
Primary home equity versus workplace retirement plans: The two-pillar middle-class engine
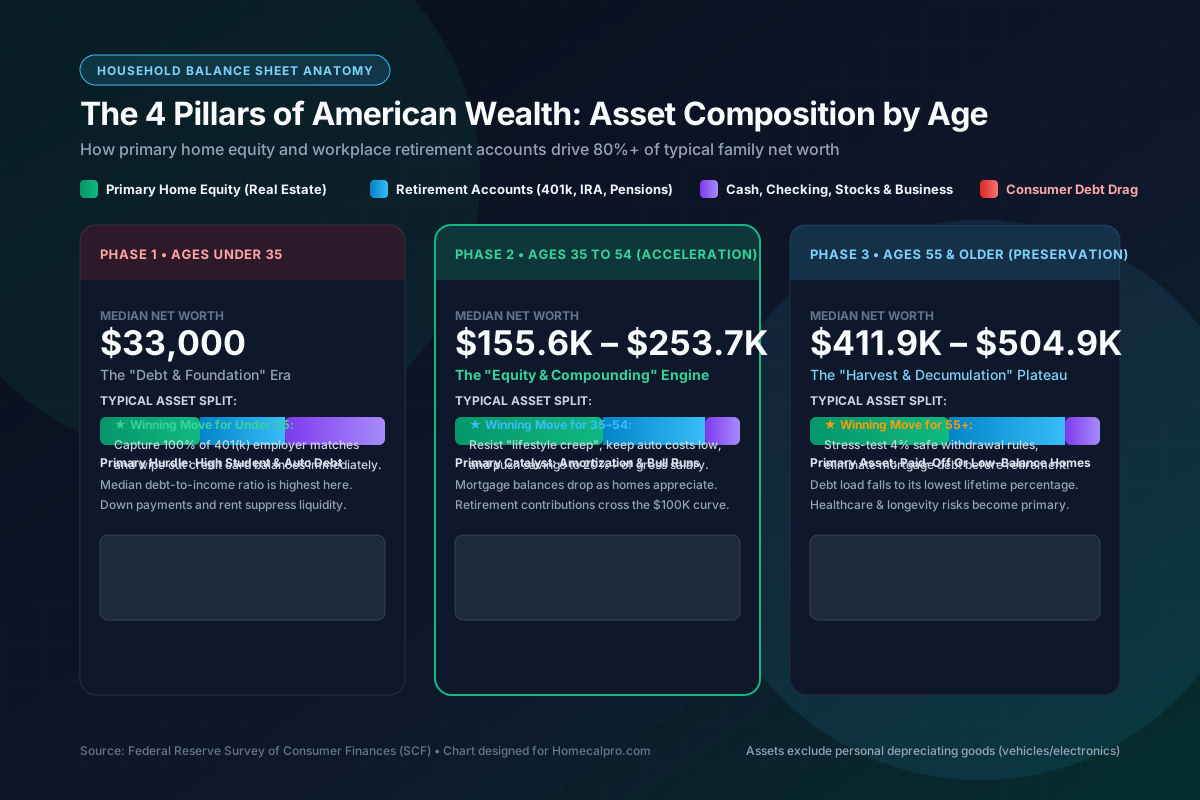
The Federal Reserve's Survey of Consumer Finances deconstructs the exact asset composition of American balance sheets. For the middle 80% of households, net worth is not made up of venture capital, fine art, or speculative crypto tokens. It is almost entirely driven by two foundational pillars: primary residence home equity and tax-advantaged retirement accounts.
The table below details how the typical household's assets and liabilities are distributed across life stages:
 AI Generated Image
| Balance Sheet Component | Percentage of Typical Median Wealth | What It Consists Of | Strategic Risk Factor |
|---|---|---|---|
| Primary Residence Equity | 45% to 58% | Market value of home minus outstanding mortgage balance | Illiquid; high property taxes and maintenance costs can cause 'house-poor' strain |
| Retirement Accounts | 30% to 42% | Traditional 401(k), Roth 401(k), 403(b), Traditional/Roth IRAs, Keogh plans | Subject to stock market volatility and pre-tax withdrawal penalties before age 59½ |
| Transaction & Cash Accounts | 5% to 10% | Checking accounts, high-yield savings (HYSA), money market funds, CDs | Vulnerable to long-term purchasing power erosion if interest rates lag inflation |
| Other Non-Financial Assets | 5% to 8% | Net equity in vehicles, tools, personal property, private business ownership | Rapid depreciation on vehicles and equipment; illiquidity in private businesses |
| Consumer Debt Drag | Negative Offset (-) | Credit cards, auto loans, student loans, medical payment plans | High revolving interest (20%+ APR) compounds backward, destroying savings rates |
5. Wealth Dispersion: Percentiles Inside Each Age Bracket
Examining the massive chasm between the 25th, 50th, 75th, and 90th percentiles
Looking solely at medians can conceal the severe wealth dispersion that exists within the exact same age group. Two 50-year-old coworkers earning identical $85,000 salaries can have wildly divergent net worths based on 20 years of housing decisions, debt habits, and 401(k) contribution rates.
The table below highlights the net worth thresholds required to enter the 25th, 50th, 75th, and 90th percentiles across key age milestones:
The 11x Divergence at Age 50
At age 50, a household at the 75th percentile ($720,000) holds over eleven times more net worth than a household at the 25th percentile ($64,500). In almost every case, the differentiator is consistent workplace 401(k) investing and avoiding high-interest revolving credit card balances.
| Age Milestone | 25th Percentile (Lower Quartile) | 50th Percentile (True Median) | 75th Percentile (Upper Quartile) | 90th Percentile (Top 10% Wealth) |
|---|---|---|---|---|
| Age 30 (Under 35 Bracket) | $5,200 | $33,000 | $128,500 | $375,000 |
| Age 40 (35–44 Bracket) | $38,000 | $155,600 | $410,000 | $1,050,000 |
| Age 50 (45–54 Bracket) | $64,500 | $253,700 | $720,000 | $1,920,000 |
| Age 60 (55–64 Bracket) | $58,000 | $411,900 | $985,000 | $2,650,000 |
| Age 70 (65–74 Bracket) | $72,000 | $431,300 | $1,150,000 | $2,980,000 |
6. The Mathematics of Closing the Wealth Gap
Three proven financial levers that move households from median to upper percentiles
If your personal net worth currently trails the median benchmark for your age, how do you catch up without exposing your family to speculative gambles? Long-term wealth creation relies on three mathematical levers:
1. Eliminate Negative Compounding (Toxic Consumer Debt): Revolving credit card balances carrying 22% to 26% APR represent mathematical cancer for personal balance sheets. While the stock market historically compounds forward at roughly 9% to 10% annually before inflation, carrying an $8,000 credit card debt compounds backward at 24%. Eliminating high-interest debt provides an immediate, risk-free 24% return on capital.
2. Automate a 15% Savings Floor: An investor who starts investing $500 monthly at age 25 at an 8% return contributes $240,000 of cash and ends up with $1,745,000 at age 65. By contrast, someone who waits until age 35 and saves $1,000 a month contributes $360,000 ($120,000 more cash) but ends up with $1,490,000. Starting earlier allows compounding to do the heavy lifting.
3. Capture 100% of Employer 401(k) Matching: If an employer matches 50% on contributions up to 6% of salary, contributing that 6% delivers an instant 50% risk-free return on day one, before the funds even begin compounding in index funds.
7. Pitfalls When Calculating Your Own Net Worth
Three common accounting illusions that mislead household financial planning
When benchmarking your household balance sheet against the Federal Reserve's SCF data, beware of three widespread calculation errors:
• The 'House-Rich, Cash-Poor' Illusion: Having a $450,000 net worth with $420,000 locked in home equity and only $3,000 in checking creates severe financial fragility. Home equity cannot buy groceries, replace a blown transmission, or cover emergency medical bills. Maintain 3 to 6 months of true liquid reserves in an FDIC-insured high-yield savings account before locking excess cash into real estate.
• Valuing Depreciating Consumer Assets: Your 2019 SUV, television sets, furniture, and personal electronics are consumer expenses, not wealth assets. Vehicles lose 15% to 20% of their value annually. Professional planners either write vehicles down to conservative wholesale trade-in value or exclude them entirely.
• Forgetting the Tax Liability on Pre-Tax Accounts: A $500,000 balance in a Traditional 401(k) or Traditional IRA is not $500,000 of spendable cash. Every withdrawal is taxed as ordinary income at your future federal and state tax rates. If your blended retirement tax rate is 20%, your spendable wealth is actually $400,000. Roth accounts, by contrast, offer 100% tax-free distributions.
8. How to Calculate Your Personal Net Worth (Step-by-Step)
A simple, disciplined formula to audit your household balance sheet twice a year
Auditing your household net worth twice a year provides an objective measurement of your financial trajectory. Use the universal accounting equation: Net Worth = Total Tangible Assets - Total Liabilities.
• Step 1: Add up tangible assets including liquid cash (checking, savings, CDs), invested portfolios (401k, IRAs, brokerage accounts, HSAs), conservative real estate equity, and business ownership stakes.
• Step 2: Add up all liabilities including outstanding mortgage balances, auto loans, student loans, and credit card balances.
• Step 3: Subtract liabilities from assets. Compare your result with the Federal Reserve median benchmark for your age cohort in Table 1 above to establish your personal baseline.
Frequently Asked Questions
Click any question below to expand quick answers, formulas, and expert tips.
What is the difference between median and mean net worth?
The median represents the exact 50th percentile of American households: half of families have more wealth, and half have less. It reflects the real-world experience of the typical middle-class family. The mean is the mathematical average (total national wealth divided by the number of households). Because the wealthiest 1% hold trillions of dollars in assets, the mean is pulled upward to roughly 4x to 5.7x higher than the median, making it a misleading metric for individual benchmarking.
Does net worth include primary home equity?
Yes. The Federal Reserve's Survey of Consumer Finances explicitly includes primary home equity in total net worth calculations. Home equity is determined by taking the estimated market value of the residential property and subtracting all outstanding mortgages, home equity loans, and HELOC balances. For the median American homeowner, home equity represents between 45% and 58% of their entire net worth.
How often is the Survey of Consumer Finances updated?
The Federal Reserve Board conducts the Survey of Consumer Finances once every three years (triennially). Because the survey involves thousands of comprehensive, in-person interviews and rigorous econometric weighting, full analysis and microdata releases typically take 12 to 18 months following the conclusion of data collection.
Why does net worth peak in the 75+ age bracket?
Median net worth often peaks in the oldest bracket due to survivorship consolidation (surviving spouses inheriting combined retirement accounts and insurance payouts) and the compounding effect of long-term real estate ownership. Over 80% of seniors in this demographic own their homes completely debt-free, having benefited from four to five decades of residential property appreciation.
The Bottom Line
When evaluating your financial health, never measure yourself against publicized 'average' net worth numbers that are heavily distorted by America's top 1%. Focus on the Federal Reserve's median benchmarks, protect a 3-to-6-month liquid cash cushion, capture 100% of your workplace retirement match, and let time and compound interest build genuine long-term wealth.
This article is for informational and educational purposes. Always verify complex calculations with a qualified professional or official documentation.
Authoritative References & Government Sources
Verify mortgage underwriting guidelines, rate statistics, and tax rules from official regulatory agencies.
- Board of Governors of the Federal Reserve System — Survey of Consumer Finances (SCF)
Official Federal Reserve triennial reports on the balance sheets, income, and wealth distribution of US families.
- Federal Reserve Bank of St. Louis (FRED) — Real Net Worth by Age of Head of Household
Macroeconomic time series charting median and average family wealth across age brackets.
- US Census Bureau — Wealth, Asset Ownership, and Debt of Households
Current Population Reports detailing household asset accumulation, debt burdens, and demographic trends.
- Bureau of Labor Statistics (BLS) — Consumer Expenditures Survey
Official federal research on consumer income, expenditure allocations, and savings rates across age cohorts.